Table of Contents
TogglePublic Insurance Registry
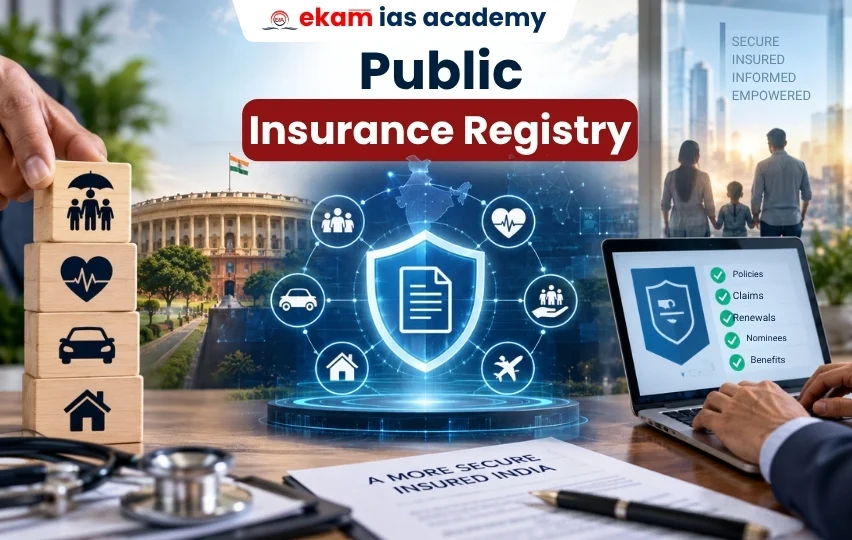
The Insurance Regulatory and Development Authority of India (IRDAI) has released a consultation paper proposing a Public Insurance Registry (PIR). The initiative seeks to create a common digital information layer for the insurance sector, similar in principle to the interoperability that helped transform India’s digital payments ecosystem through UPI.
UPI and the Digital Public Infrastructure Model
The Unified Payments Interface (UPI) demonstrates how Digital Public Infrastructure (DPI) can transform an entire sector through interoperability, simple foundational building blocks and federated architecture. Under a federated model, information remains with the organisation that originally holds it rather than being concentrated in one central database.
The proposed PIR seeks to apply these principles to insurance while allowing different insurers and systems to remain operationally independent.
Challenges in the Insurance Sector
Insurance customers currently face several information-related difficulties. KYC procedures may need to be repeated, while policy and claims information is often fragmented across insurers.
Limited access to verified information can also make it difficult for consumers to compare products, understand their coverage and switch providers. The PIR aims to promote an ecosystem in which insurance is increasingly purchased through informed consumer choice, rather than depending primarily on intermediaries for information.
The Missing Digital Connective Layer
Several recent initiatives provide important building blocks for insurance digitisation. These include the Sabka Bima Sabki Raksha Act, the Digital Personal Data Protection Act and Bima Sugam.
The PIR is proposed as the connective layer that can allow these developments to function within a more interoperable information ecosystem.
Key Design Principles of PIR
The registry is based on two important principles. First, it would provide minimalist building blocks, rather than controlling the detailed functioning of insurers. Second, its federated architecture would keep data with source systems, helping reduce the risks associated with centralised storage of sensitive insurance information.
What Can PIR Offer Stakeholders?
For Policyholders
Customers could obtain a consolidated view of their life, health, motor and property insurance policies, including renewals, nominees, claims and unclaimed benefits.
For Insurers
Verified policy and claims information could improve underwriting, fraud detection and risk assessment, while standardised information exchange could reduce compliance-related costs.
For Regulators and Reinsurers
Consolidated exposure information could strengthen regulatory supervision and catastrophe-risk preparedness.
Governance Structure
The proposal envisages restructuring the Insurance Information Bureau (IIB) into a not-for-profit entity wholly owned by IRDAI. The model emphasises independent execution, institutional neutrality and rotating industry representation.
Significance and Challenges
If implemented effectively, PIR could improve insurance penetration, portability, claims processing, fraud control and transparency. However, its success will depend on strong data privacy, consent mechanisms, governance independence, participation incentives and interoperability.
Conclusion
The Public Insurance Registry represents an attempt to build Digital Public Infrastructure for insurance. By improving information availability while retaining a federated approach to data, it seeks to reduce friction for consumers and create a more transparent and efficient insurance ecosystem.
FAQs: Public Insurance Registry (PIR)
What is the Public Insurance Registry (PIR)?
The Public Insurance Registry (PIR) is a proposed digital infrastructure initiative by IRDAI to create a common, interoperable information layer for India’s insurance sector.
How is PIR similar to UPI?
PIR seeks to apply principles used by UPI and Digital Public Infrastructure, particularly interoperability, minimalist building blocks and a federated architecture, to the insurance ecosystem.
What benefits could PIR provide to policyholders?
Policyholders could potentially access a consolidated view of their life, health, motor and property insurance policies, including renewals, nominees, claims and unclaimed benefits.
How could PIR help insurance companies?
Verified and standardised information could support better underwriting, fraud detection and risk assessment, while reducing information-related and compliance costs.
What are the major challenges in implementing PIR?
Key challenges include data privacy, consent mechanisms, governance independence, participation incentives and interoperability among different insurance-sector systems.